



Between 1975 and 1979, inflation averaged about 16% a year in the UK and about 8% in the US. Ten-year gilts yielded 13.2% on average and US treasuries 8%. Once rising prices were taken into account, lending to the government was a lousy proposition.
Then the economic regime began to change. UK inflation peaked at 21.8% in May 1980, and US inflation at 14.8% two months earlier. Bond yields topped out about 18 months later, at 16.3% on 10-year gilts and 15.8% on treasuries. A multi-decade bull market in bonds followed.
Bull market in bonds from early 1980s to 2020 – US and UK 10-year government bond yields
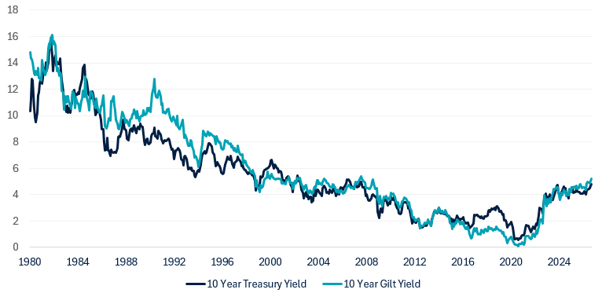
Source: Schroder Diversity Real Return Team, LSEG Datastream, September 2026.
By 2020 it had run out of road. Ten-year gilts yielded just 0.1% and treasuries 0.5%. Global government bond yields reached their lowest level in more than a century of recorded history. Backward-looking returns were strong.
On a forward-looking basis, however, there was scant reward on offer for even patient investors. With yields below zero after inflation, bonds were once again certificates of confiscation and investors had a great deal to lose if growth or inflation recovered. Both did, and bond prices fell sharply.
Six years on, the market presents a different opportunity. Ten-year gilts now yield about 5.5% and treasuries about 5.3%. That provides a positive real return, with a modest cushion.
That is not to say the backdrop is benign. Inflation is uncomfortably high and likely to rise into 2027. The US fiscal picture has become a structural maths problem, with large and persistent deficits and no simple solution.
Meanwhile, protectionist policies that prioritise national interests and economic security over 'free' market economic growth are driving changes to global trade agreements, supply chain management and access to commodities. Oil prices are higher as a result.
Paradoxically, running economies 'hot' – tolerating higher inflation in pursuit of stronger growth – may prove the necessary long-term answer to these problems, even if it causes trouble along the way. Economic and market conditions are ostensibly positive but feel unstable. This is also why government bonds are out of favour.
That said, as much as fundamentals matter, so do valuations. And bond prices have adjusted materially in recent months.
One old rule of thumb we have always found instructive is, over the long term, government bond yields should sit roughly in line with the trend rate of nominal GDP growth.
When yields are above that level, bondholders are being fairly paid for the conditions they face. Yields below it are generally less constructive. In the UK, trend nominal growth is between 3.5% and 4.5%, and a little higher in the US. Against that benchmark, yields at or above 5% look adequate.
GDP is, of course, backward-looking, while markets price the road ahead. Yet when market pricing is weighed against what the future may hold, the risk-reward looks better than it has for some time.
Nominal UK GDP growth (YoY) vs 10-year UK gilt yield
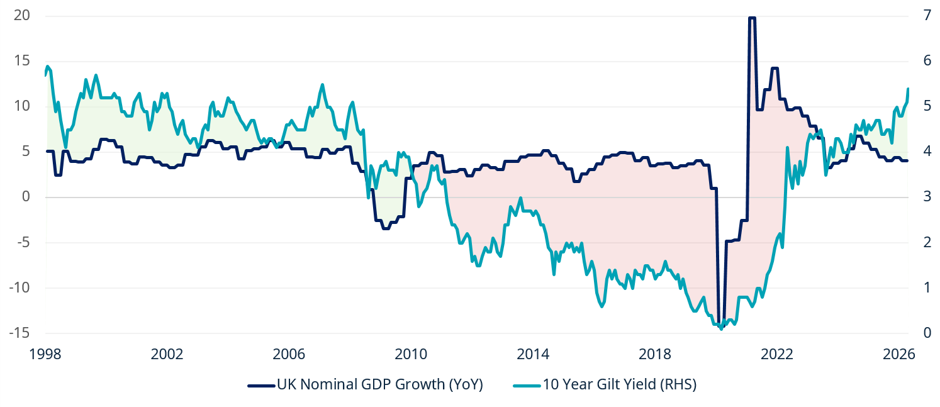
Source: Schroder Diversity Real Return Team, Bloomberg, September 2026.
Start with inflation. Cyclical forces bring upside risks to inflation, but with them downside risks to real growth. This equilibrium could resolve higher, as it did between 2021 and 2023.
Missing today, however, is the cocktail that fuelled that episode: rapid money supply growth, fiscal expansion, excess household savings and pent-up demand. Artificial intelligence is a bit of a wildcard on the productivity side, but we would not form a base case around a step-up in nominal GDP growth on a multi-year basis from current levels.
Then there is monetary policy. Central banks look set to tighten, but the market is already pricing in 100 basis points of rate rises in the UK by the middle of next year and 75 basis points in the US. That raises an obvious question: if the Bank of England were to raise rates four times, could the UK economy handle it, and for how long?
Finally, consider the role bonds play. A shift from negative to positive equity-bond correlations has belatedly caused investors to question whether bonds still belong in their portfolios.
However, giving up on the asset class offering any utility under risk-off conditions is a bit like closing the barn door after the horse has bolted. Disinflationary and even deflationary outcomes remain possible over the medium term. For government bonds, the horse has returned to the stable, providing optionality under that scenario.
None of this calls for a strategically bullish view on government bonds and duration. But from a tactical perspective, the landscape is shifting.
It is worth putting some numbers on this. An investor who bought 10-year gilts in August 2020, when yields were at their all-time low, would earn a total return of 0.77% over 10 years, assuming a static reinvestment rate. At today's yield, the same assumptions would produce a total return of close to 70%. That is a sizeable difference.
Regimes change, and so do valuations. The job is to adapt.
Robin McDonald is a fund manager and head of multi-manager at Schroders. The views expressed above should not be taken as investment advice.