

The current credit cycle is being defined by dispersion between issuers rather than a broad deterioration in credit quality, according to Man Group’s credit team.
In a new report, the team noted that fundamentals remain resilient overall and income continues to support returns but argued that tighter valuations leave less room for error and make issuer selection increasingly important.
The credit cycle outlook could also be disrupted depending on the duration and severity of the war in the Middle East, the report added.
Below, the credit team sets out where it sees resilience, rising risks and selective opportunities across private credit, high yield, emerging market corporates and investment grade.
Private credit
The report noted that private credit remains supported by strong income generation and relatively contained realised losses, despite a series of high-profile defaults across software and software-as-a-service (SaaS) names attracting attention.
However, the credit team noted that higher non-accruals, lower recovery rates and signs of stress beneath headline figures mean investors need to focus more closely on individual borrowers – particularly those exposed to technological disruption and economic change.
High yield and leveraged loans
The Man Group credit team said high-yield fundamentals remain “reasonably sound”, supported by improved average credit quality and borrowers that refinanced at low fixed rates before yields rose.
However, they warned that tight spreads leave investors with little protection if conditions weaken.
The report noted that leveraged loan borrowers are also more vulnerable to prolonged high interest rates because their floating rate debt feeds through to financing costs more quickly.
Against this backdrop, the Man Group credit team sees potential opportunities among companies facing refinancing gaps, liquidity pressures or complex capital structures, that require tailored financing solutions.
Emerging market corporates
The report noted that the Man Group credit team remains constructive on emerging market corporate debt, arguing that many issuers have materially stronger balance sheets than their developed market counterparts, while also offering wider spreads.
Emerging market corporate spread premium vs the US
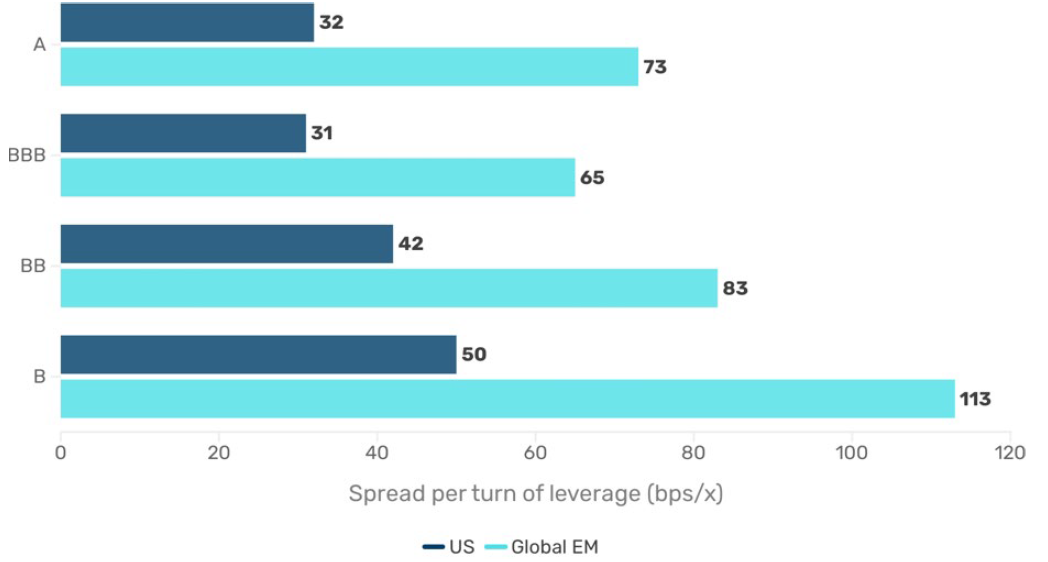
Source: Man Group, Bank of America Global Research. As of 30 September 2026.
The report noted that this premium reflects sovereign, political and macroeconomic risks more than underlying corporate fundamentals, although elevated dispersion and full valuations mean investors should remain selective.
Investment-grade
Higher government bond yields have improved the income available from investment-grade credit, according to the Man Group report.
As shown in the graph below, periods when 10-year US treasury yields exceeded 5.25% were followed by positive 12-month returns for global investment-grade bonds.
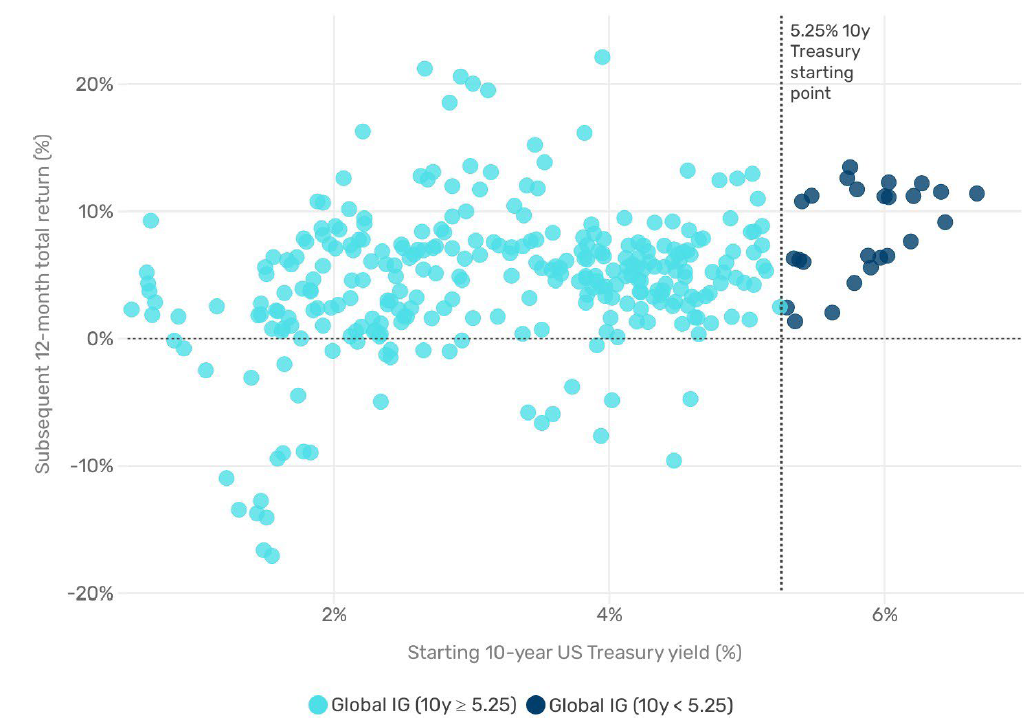
Source: Man Group. 12-month return of ICE Global Large Cap Corporate Index USD Hedged plotted against starting month-end US Treasury 10-year yield. Month-end data from 1 January 1999-15 September 2026.
However, the credit team warned that growing AI-related borrowing by hyperscalers is creating new concentration risk, with the long-term outlook dependent on whether heavy investment in AI infrastructure ultimately generates the expected cashflows.