



Jefferies has started coverage of three emerging markets investment trusts, rating two as a ‘buy’ and one as a ‘hold’.
In its initiation note, the broker said it favoured Fidelity Emerging Markets and Templeton Emerging Markets for their exposure to “AI-driven semiconductor demand, China’s clean energy leadership and improving governance”.
It also said that “their lack of performance fees and use of continuation votes are shareholder-friendly features”.
Fidelity Emerging Markets is the broker’s preferred route into the asset class. Jefferies analysts Fiona Huang and Matthew Hose described it as “a bullish play on emerging markets, given the portfolio’s geared exposure to attractive themes across multiple geographies”.
The £521m trust has achieved a maximum FE fundinfo Crown rating of five and gives “access to a strongly performing manager through a cost-effective structure”, with no performance fee and a lower fixed management fee than its open-ended counterpart.
It has a conditional tender offer and a periodic continuation vote. Jefferies noted that the discount had narrowed on the back of NAV performance: according to Trustnet data, the discount is currently at 6.6% while the five-year average is 11.4%.
The trust returned 59.2% over one year and 165.8% over three years to the end of September, as the chart below shows. Telecom, media and technology made up 60.1% of the portfolio at the end of August.
Performance of trusts against index and sector over 1yr
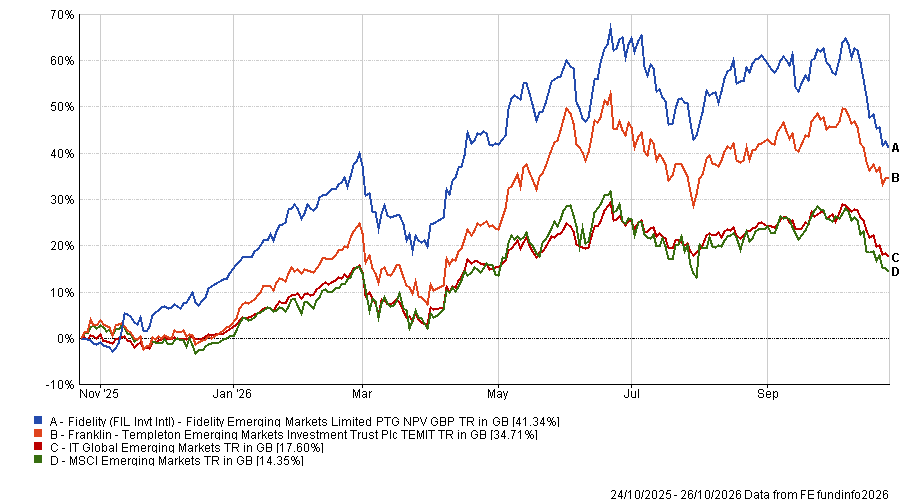
Source: FE Analytics
Templeton Emerging Markets Investment Trust got a ‘buy’ for what Jefferies called “geared exposure to high-quality growth stocks”. The broker said the manager’s “concentrated, stock-driven approach is supported by a strong track record of NAV performance and should be particularly well-suited to a bullish market environment”.
The trust remains “a compelling vehicle for emerging markets exposure” despite its recent run, which it put down to strength in technology holdings.
The £2.7bn trust launched in 1989 and is run by Chetan Sehgal and Andrew Ness. It returned 31.3% this year to the end of September, 54.2% over one year and 143.5% over three years. Over five years, its 110.5% return beat Fidelity Emerging Markets’ 88.8%. Technology-related sectors account for 54.4% of the portfolio.
The research house RSMR also rates the trust. Its analysts said Templeton “leverages the huge research resource” of its parent, which includes meetings with around 2,000 companies a year.
The team’s valuation focus is “not a deep value approach”, which means the managers can add some growth stocks to the portfolio. The analysts concluded the trust is suitable as a core holding for emerging market equities.
Finally, VinaCapital Vietnam Opportunity was given a ‘hold’ rating from Jefferies. Huang and Hose said the Vietnamese market is relatively difficult to access and that the fund’s private equity portfolio sets it apart.
However, they added: “We do not believe historical returns have adequately compensated investors for the additional risks associated with this part of the portfolio.”
The analysts also questioned the performance fee, which they said is “unusual among emerging markets funds, particularly as it is calculated relative to a benchmark despite the manager pursuing an ostensibly benchmark-agnostic investment strategy”.
The trust has recently introduced a new fee policy, whereby in the event of underperformance, performance fees will be clawed back at the same 3bps rate, subject to a maximum clawback of 0.2% of net asset value (NAV). The clawback applies beyond the performance fee, meaning it could be used to reduce the base management fee if underperformance is severe.
For the Jefferies analysts, the new clawback provisions do favour shareholders and recent underperformance means the revised fee structure is “likely to work in shareholders’ favour in the near term”.
The £496.6m trust lost 9.6% over one year and gained 4.8% over three years and 6.7% over five. Its annual management charge is 1.95%.
Performance of trust against index and sector over 1yr
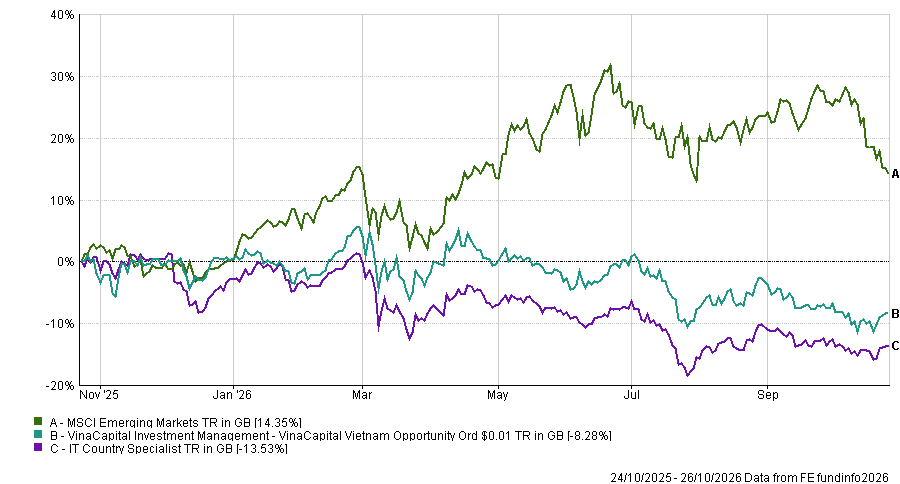
Source: FE Analytics
While the trust is the least volatile of the three, with a one-year volatility of 16.2%, its Sharpe ratio, which measures return per unit of risk, is -0.02, against 1.67 for Fidelity Emerging Markets and 1.57 for Templeton Emerging Markets.